🔹 Inflation cooled, and the Fed just got room to wait.
Stocks set fresh records as Hegseth confirms the Iran ceasefire and oil retreats nearly 4%.
Good afternoon,
Yesterday's inflation report did exactly what the calm-headed were hoping: it came in tame. Consumer prices rose just 0.1% in July, with annual inflation easing to 3.4% and core inflation to 2.5% — the second straight month of cooling. That gives the Federal Reserve room to hold rates steady in September rather than hiking, which is why stocks sit near records and gold near a ten-week high. But the job isn't finished: producer prices land this morning, and after a benign consumer number, that's the one that could still stir things up. In my view, the inflation picture is improving — just not settled.

SpaceX's IPO made history. The stock hit $165 in a week.
But the most important part of this story may not be the rockets.
It's Starlink. T-Mobile just enabled Starlink satellite connectivity on every iPhone and billions of phones are coming online for the first time.
Starlink sells them the connection. That's where its job ends. But every hour those people spend on their phones generates ad revenue - and someone has to collect it.
I found the company doing it. 490 million users. A billion dollars earned and saved. 32,481% revenue growth - enough to make it the #1 software company according to Deloitte's fastest growing companies list in 2023. $11.8 million in EBITDA in 2025. And it hasn't gone public yet.
But on August 14, the opportunity to invest at this price closes — and it's gone after that.
Every previous round sold out. I don't expect this one to last either.
View the full offering before August 14 →
(Sponsored content)
What Moved the Market
The levels below are Wednesday's August 12 close — the last confirmed session — with this morning's data labeled separately.
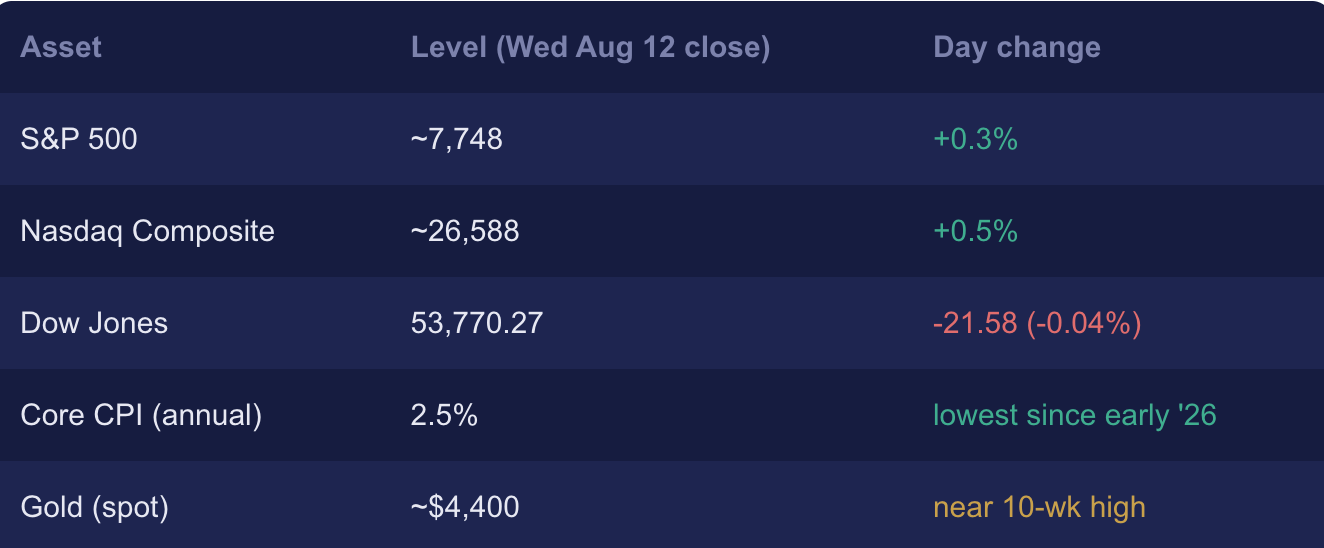
Socks rose but faded from bigger opening gains — a sign the tame CPI was already priced in.
Here's what drove it:
- Inflation cooled, as hoped. July headline CPI rose 0.1% for the month and 3.4% for the year, down from 3.5%. Core inflation eased to 2.5%, its slowest annual pace in months — both matching economist forecasts.
- The Fed got breathing room. Markets read the report as narrowly clearing the bar for the Fed to hold rates steady in September, with hike odds easing back toward 40%.
- But stocks faded their pop. All three indexes opened sharply higher — the Nasdaq briefly up more than 1% — then gave back most of the gain, a classic sign the news was already priced in.
- AI earnings stole the show. CoreWeave jumped 18% after narrowing its loss, Super Micro rose 9% on an upbeat forecast, and Nebius surged more than 12% on strong results.
- Oil kept its premium. U.S. crude pushed above $83 as hopes for reopening the Strait of Hormuz faded, keeping a floor under inflation worries.
- The dollar reversed higher after the data, and today brings the producer price index plus weekly jobless claims.
A tame inflation number was the outcome patient investors wanted, and it keeps the Fed on hold for now. But the muted market reaction tells you the good news was expected. The real swing factor today is producer prices — and with oil still elevated, that number carries genuine two-way risk.
Earnings
The season's tail delivered a strong showing from the AI infrastructure names.
- CoreWeave climbed 18% after narrowing its quarterly loss and meeting revenue expectations — a reassuring read on demand for AI computing capacity.
- Super Micro Computer rose 9%, beating on earnings and offering an upbeat first-quarter forecast, though it fell just short on revenue.
- Nebius Group surged more than 12% on better-than-expected revenue, earnings, and margins — another sign the AI build-out is still translating into results.
- Applied Materials reports after today's close, the week's last major read on the semiconductor equipment cycle.
The AI-infrastructure trade got a genuine boost — three names that supply the picks and shovels of the build-out all delivered. It's evidence the enormous spending is still producing revenue for the companies enabling it, which is exactly what a jittery market needed to see.
Gold & Silver Moves
My corner, and gold is holding its hard-won gains. It's trading near $4,400 in spot terms, having pushed to a ten-week high after the tame CPI, and is up nearly 10% over the past month and more than 30% from a year ago. Silver sits near $65.58, just off a seven-week high. The gold/silver ratio holds in the high 60s.
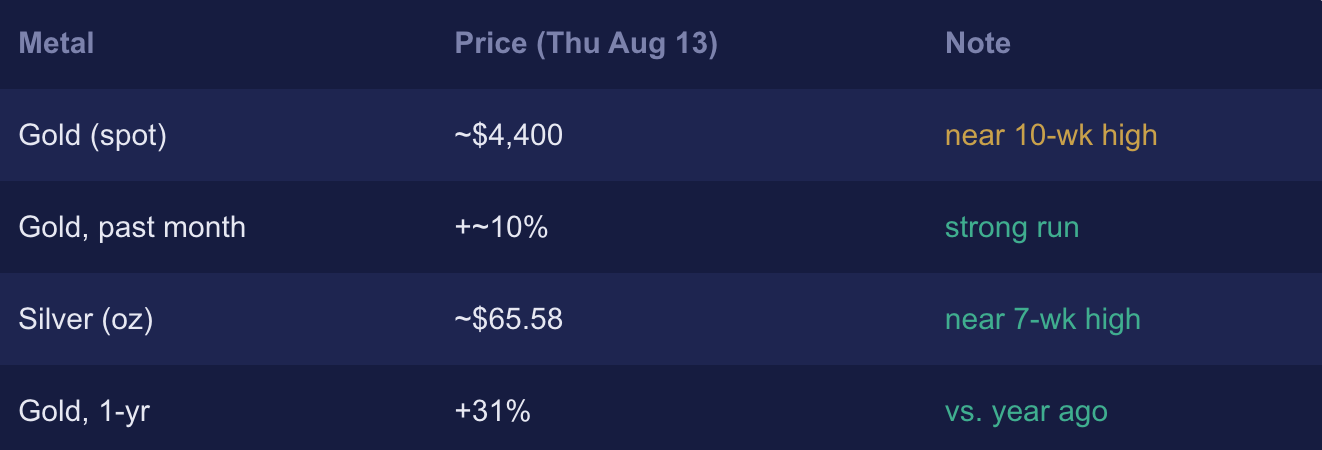
Gold up 10% in a month with silver near a seven-week high. The metals are having their strongest stretch of the year.
Here's the read, and it ties the whole month together. Gold pays you nothing, so its rival is what a bond yields after inflation. Yesterday's cooler CPI reduced the odds of a Fed hike, which eased the pressure on gold and let it hold near its ten-week high. Combined with last week's weak jobs report, the message is consistent: a softening economy buys the Fed time, and a patient Fed is good for gold.
But here's the detail I most want you to sit with, because it's the heart of the thesis. In the days before the CPI, gold climbed despite a firmer dollar, higher Treasury yields, and rising oil — three forces that, in any textbook, should have pushed it down. As one veteran dealer put it, that gold advanced anyway tells you demand, not interest rates, is setting the price. Steady Chinese institutional buying and central-bank accumulation continued straight through. That's the structural bid I keep returning to, and it's why this run has staying power that a single data point can't easily undo.
My usual caution, and today it's specific: producer prices land this morning, and I'd remind you these numbers can surprise. A hot PPI could firm the dollar and yields and knock the metals back, just as a tame one could extend the run toward the $4,500 area technicians are watching. Silver, near $65.58 and backed by its sixth straight annual supply deficit, remains the one to watch for conviction.
Gold is up 10% in a month and holding near a ten-week high because demand — central banks, Asian buyers — is setting the price, not just rate bets. Today's producer-price number may jostle it, but the structural support underneath doesn't rest on any single report.
The Deal Room
- AI infrastructure: The trio of CoreWeave, Super Micro, and Nebius all rallying on results underscores that capital keeps flowing into the physical backbone of artificial intelligence — data centers, servers, and computing capacity.
- Sovereign wealth: Norway's $2.3 trillion sovereign wealth fund reported a record half-year profit of more than $182 billion, powered by a rally in Asian technology stocks — a reminder of how globally this AI-led advance reaches.
- Treasury supply: A $42 billion 10-year Treasury auction was on the calendar, a live test of investor appetite for government debt at a time when long yields sit near multi-decade highs.
The AI build-out keeps drawing capital from every corner — from cloud startups to the world's largest sovereign fund. But that Treasury auction is the quiet counterpoint: with yields elevated, how willingly investors keep funding government borrowing is a story worth watching into the fall.
Retirement Lens
So what does this post-inflation Thursday mean for someone holding stocks, bonds, and a little gold?
Mostly, it's a moment of quiet reassurance. The number that could have upset everything came in benign, and a balanced portfolio responded exactly as designed: stocks near records, gold near a ten-week high, bonds steady. This is what a good week looks like when the data cooperates — not fireworks, just each piece doing its job.
The honest note of caution is that the inflation story isn't fully closed. Producer prices this morning, more consumer data next month, and stubbornly elevated oil all mean the Fed's September decision remains genuinely open. That's not a reason to act; it's a reason to stay attentive and patient rather than assuming the all-clear.
If there's a lesson worth carrying, it's the one from gold this month: the steadiest returns often come from owning quality assets through the uncertainty and letting demand and time work, rather than reacting to each headline. Read today's number calmly, and let your allocation carry you toward the weekend.
Recommended Reading
- July CPI comes in tame — A clear breakdown of the inflation numbers and why they give the Fed room to hold in September.
- The Starlink playbook and the $0.52 Chicago startup (ad)
- S&P 500 stays near records after mild inflation — Good on why stocks faded their opening pop and what it signals about expectations.
- Gold edges up as investors await PPI — Useful on why the cooler CPI and softer dollar are supporting gold into today's producer-price data.
The Bull Investor is for informational and educational purposes only and is not investment advice. I am not your financial advisor. Do your own research before making any decision.
— Anthony
Please read the offering circular and related risks at invest.modemobile.com . This is a paid advertisement for Mode Mobile’s Regulation A+ Offering.
Mode Mobile recently received their ticker reservation with Nasdaq ($MODE), indicating an intent to IPO in the next 24 months. An intent to IPO is no guarantee that an actual IPO will occur.
The Deloitte rankings are based on submitted applications and public company database research, with winners selected based on their fiscal-year revenue growth percentage over a three-year period