🔹 Markets are holding their breath for tomorrow's inflation number.
Stocks set fresh records as Hegseth confirms the Iran ceasefire and oil retreats nearly 4%.
Good afternoon,
The market spent Monday in a holding pattern, and this morning it's much the same: stocks are near record highs but hesitant, waiting for tomorrow's July inflation report before making the next move. Gold, meanwhile, isn't waiting — it climbed to a two-month high today as investors position defensively ahead of that number. In my view, the whole market has narrowed its focus to a single data point due Wednesday morning, and the calm you see today is the quiet before that test. Positioning ahead of it is a gamble; understanding it is not.

Apple’s Starlink Update Sparks Huge Earning Opportunity
Apple just secretly added Starlink satellite support to iPhones through iOS 18.3.
One of the biggest potential winners? Mode Mobile.
Mode’s EarnPhone already reaches 490M+ users that have earned over $1B, and that’s before global satellite coverage. With SpaceX eliminating "dead zones" worldwide, Mode's earning technology can now reach billions more in unbanked and rural populations worldwide.
Their global expansion is perfectly timed, and you still have a chance to invest in their potentially pre-IPO offering before it closes.
59,000+ investors participated in Mode’s previously sold out offering and limited space remains in the current round.
With their recent 32,481% revenue growth and newly reserved Nasdaq ticker, Mode is one step closer to a potential IPO.
Join 59,000+ investors before Mode’s pre-IPO offering closes.
(Sponsored content)
What Moved the Market
The levels below are Monday's August 10 close — the last confirmed session — with this morning's moves labeled separately.
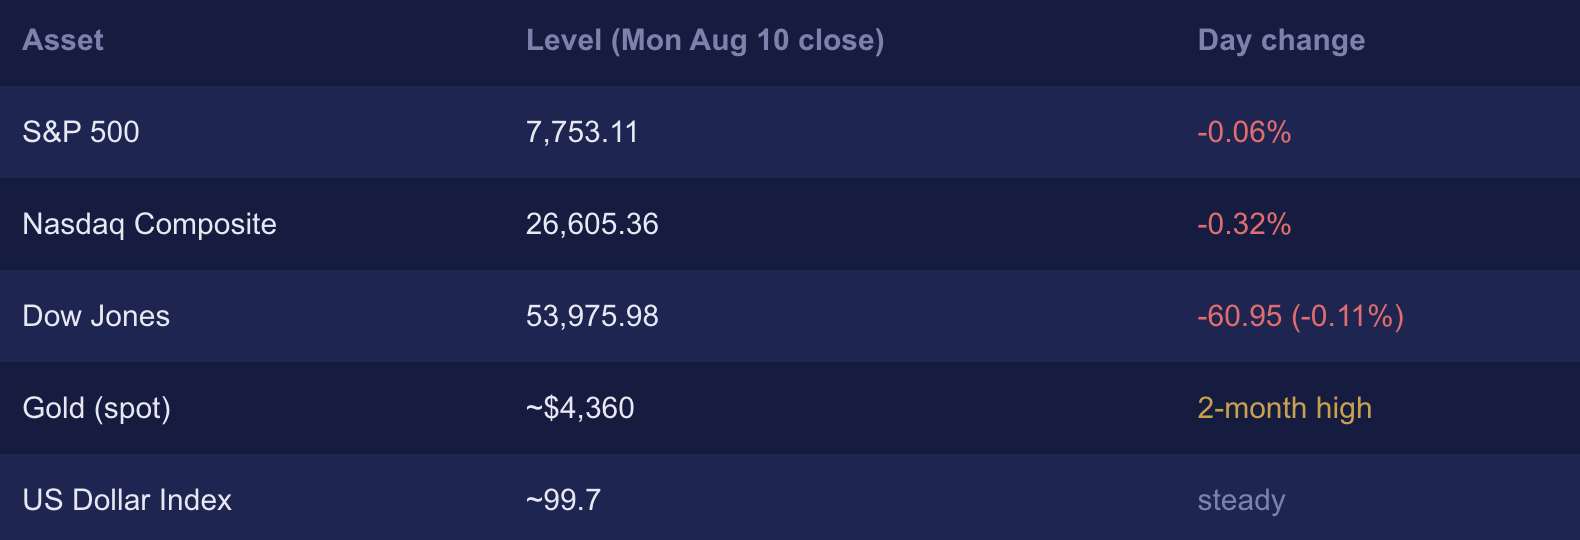
Stocks pausing just below records while gold pushes higher. Money is hedging ahead of the data.
Here's what's shaping the session:
- Stocks paused after a huge week. All three major indexes slipped modestly Monday, digesting the prior week's rally — the S&P's best since April — rather than reversing it.
- Oil kept climbing. Crude rose again on continued uncertainty over the Strait of Hormuz, after Iran denied direct U.S. talks over the weekend and renewed its demands. Higher oil is the one thing that could unsettle the inflation picture.
- Nvidia pulled back, weighing on the Nasdaq, even as Bank of America reiterated a buy rating and called it a top pick ahead of its late-August earnings.
- Rate-hike odds stayed low. After Friday's weak jobs report, markets put the odds of a September hike at roughly 42% to 44% — a sharp drop from two weeks ago.
- Critical minerals made news. The Trump administration backed an Australian scandium mine to challenge China's dominance in critical minerals, and Sunrise Energy Metals surged as much as 29% on a $400 million U.S. investment.
- The main event is tomorrow. July's Consumer Price Index lands Wednesday at 8:30 a.m., with producer prices Thursday and retail sales Friday.
This is a market catching its breath. After a powerful rally on the hope that a cooling economy means a patient Fed, investors want tomorrow's inflation number to confirm that story before pushing higher. The modest Monday dip isn't weakness — it's discipline ahead of a genuine test.
Earnings
The season's final meaningful reports arrive this week, with a clear focus on technology and the consumer.
- Cisco reports tomorrow after the close, a bellwether for corporate technology spending and networking demand tied to AI.
- Applied Materials follows Thursday, a key gauge of whether the semiconductor equipment boom that has powered this market is still accelerating.
- Super Micro Computer reports early this week, another read on the appetite for AI server infrastructure.
- The broader season was strong, with second-quarter S&P 500 earnings growth tracking above 20% — the solid foundation beneath the summer's volatility.
With most of corporate America having reported a genuinely good quarter, these remaining names are about confirming the AI-spending trend, not rewriting it. For a diversified holder, the earnings verdict is in, and it was encouraging.
Gold & Silver Moves
My corner, and the metals are doing something worth pausing on: rising into the inflation report rather than waiting for it. Gold climbed to a two-month high, trading near $4,360 in spot terms with futures around $4,399, as investors moved into safe havens ahead of the data. Silver holds firm near $63.80 to $64. The gold/silver ratio sits in the high 60s.
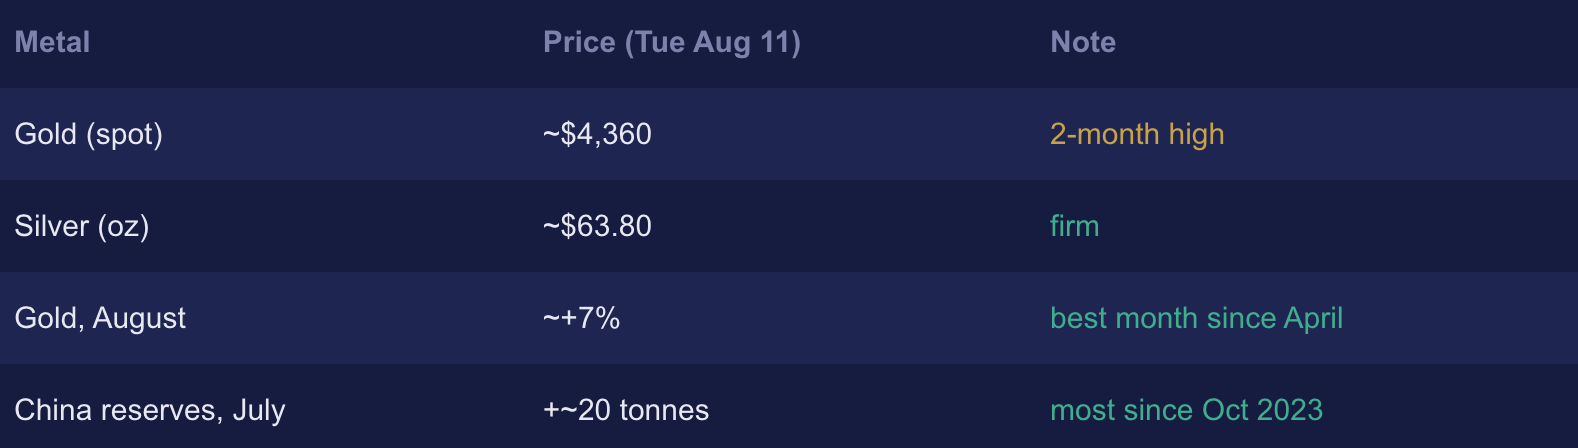
China's central bank adding 20 tonnes in a single month. That's the structural buyer beneath the price.
Here's the read, and today it's the structural side of the story that deserves the spotlight. Gold pays you nothing, so its rival is what a bond yields after inflation — and with a hike now unlikely, that pressure has eased, which is why gold sits at a two-month high. But the more durable force is who's buying. China's central bank added roughly 20 tonnes to its reserves in July, its largest monthly increase since October 2023, after 15 tonnes in June. Gold-backed ETFs just posted their longest inflow streak in months.
This is the part I keep coming back to because it doesn't move with the daily headlines. Central banks and long-term investors are steadily accumulating gold as a hedge against currency and debt risks — the same risks that pushed the 30-year Treasury yield to a two-decade high just last week. That buying provides a floor beneath the price that a single inflation report can't dislodge.
Tomorrow's CPI is still a real near-term test, and I won't pretend otherwise. A hot number — and some economists see upside risk from tariffs — could trigger profit-taking through a stronger dollar and higher yields. A soft one likely extends the run, with some technicians eyeing the $4,500 region. But whichever way tomorrow breaks, the structural bid remains.
Gold is at a two-month high partly on rate hopes, but the deeper support is relentless central-bank buying — China alone added 20 tonnes in July. Tomorrow's inflation number may swing the price short-term; the structural demand underneath it isn't going anywhere.
The Deal Room
- Critical minerals: The U.S. government's backing of an Australian scandium mine, and its $400 million investment lifting Sunrise Energy Metals as much as 29%, signals a strategic push to reduce dependence on China for critical minerals — a theme worth watching for the long term.
- Chips: Nvidia drew a fresh buy reiteration from Bank of America, which called concerns about memory costs and circular financing "overblown" ahead of the company's late-August earnings.
- Storage strength: Morgan Stanley upgraded several enterprise hardware names, arguing that "chipflation" is accelerating rather than delaying corporate server and storage spending.
Beneath the index-level calm, capital is rotating with real purpose — into critical minerals, into enterprise hardware, into the picks-and-shovels of the AI build-out. For a diversified holder, these shifts are happening inside what you already own, without a single trade required.
Retirement Lens
So what does this wait-and-see Tuesday mean for someone holding stocks, bonds, and a little gold?
Mostly, it's a day that rewards doing nothing gracefully. The market itself is waiting for tomorrow's inflation number, and there's real wisdom in matching that patience rather than trying to outguess the data. Your stocks are near records. Your gold is at a two-month high. Your bonds have steadied. Every piece is working — which, again, is precisely when the urge to tinker should be met with a firm no.
The honest truth about tomorrow's CPI is that its direction is genuinely uncertain, and the risk cuts both ways — a cool print extends the good mood, a hot one revives the rate debate. Trying to position ahead of a coin flip tends to cost more than it earns.
What I'd hold onto is the structural note from the metals: the steadiest buyers in the world keep accumulating gold, unbothered by any single day's data. That's the long view a retirement portfolio is built on. Read tomorrow's number calmly, and let your allocation carry you.
Recommended Reading
- Gold and silver rebound ahead of US CPI — A clear technical and fundamental read on why a weak dollar is supporting the metals into Wednesday's data.
- Monday's market recap — Good on the pre-CPI pause, the oil bounce, and the Nvidia pullback.
- Apple’s Starlink Update Sparks Huge Earning Opportunity (ad)
- Gold and silver await key inflation data — Useful summary of where the metals sit and what the week's data could mean for Fed expectations.
The Bull Investor is for informational and educational purposes only and is not investment advice. I am not your financial advisor. Do your own research before making any decision.
— Anthony
Please read the offering circular and related risks at invest.modemobile.com . This is a paid advertisement for Mode Mobile’s Regulation A+ Offering.
Mode Mobile recently received their ticker reservation with Nasdaq ($MODE), indicating an intent to IPO in the next 24 months. An intent to IPO is no guarantee that an actual IPO will occur.
The Deloitte rankings are based on submitted applications and public company database research, with winners selected based on their fiscal-year revenue growth percentage over a three-year period